September 23, 2026
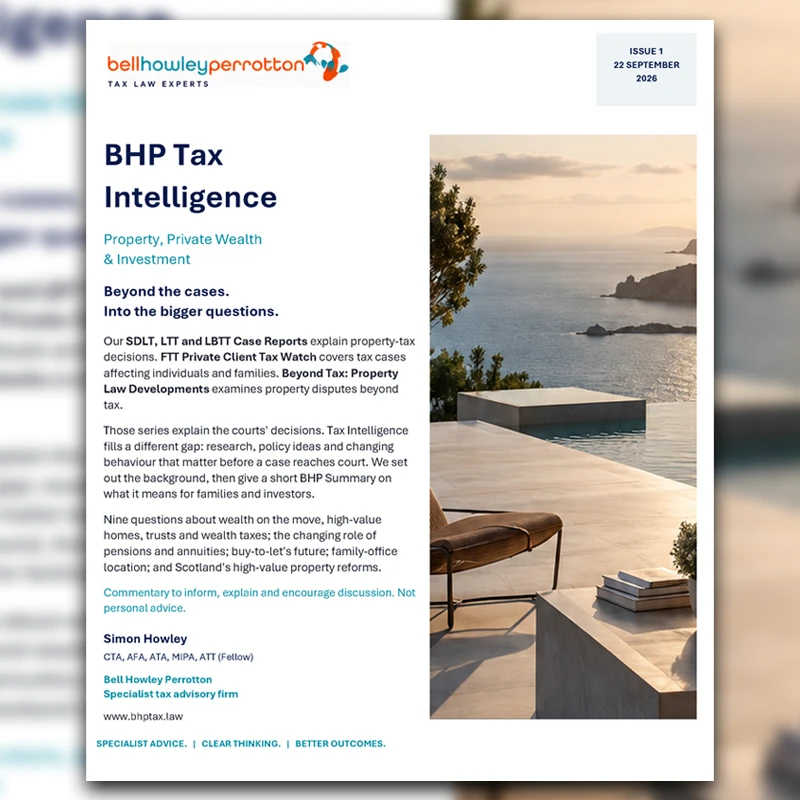
I’m pleased to share the first consolidated issue of BHP Tax Intelligence | Property, Private Wealth & Investment which you can download here.
This publication is deliberately different from our case-law reports.
Our SDLT, LTT and LBTT Case Reports, FTT Private Client Tax Watch and Beyond Tax: Property Law Developments primarily examine decided cases and legal developments.
BHP Tax Intelligence looks beyond the cases.
It considers the wider tax, wealth, property and investment questions that may shape decisions before they ever reach a tribunal or court.
In this issue, we look at nine areas:
• Wealth on the move – what the available data can, and cannot, really tell us about wealthy individuals leaving the UK.
• High-value homes – who should be allowed to defer the proposed High Value Council Tax Surcharge, and how hardship should be identified.
• Offshore trusts – when does a trust still serve a useful family or governance purpose, and when has the structure simply become expensive inertia?
• Taxes on wealth – should the UK fix weaknesses in existing taxes before introducing another tax on wealth?
• Inheritance tax and pensions – why the April 2027 changes require families to reconsider the order in which assets are spent, retained or gifted.
• Buy-to-let – whether the sector is moving from a relatively passive investment model towards a more operational and professionally managed business.
• Annuities – why guaranteed retirement income is becoming strategically relevant again for some older and wealthier pension holders.
• Family offices – why jurisdiction choice starts with residence, control, substance and decision-making rather than a licence or a low headline tax rate.
• Scotland and high-value property – whether new Council Tax bands should be assessed alongside the highly concentrated residential LBTT base.
The aim is not to produce another technical update.
Each article asks a broader question, explains the issue in straightforward language and ends with a BHP Summary setting out our view of what matters.
The underlying sources are identified and attributed. BHP’s commentary is separately expressed and intended to challenge assumptions, encourage debate and prompt better questions.
This is general commentary and opinion, not individual tax, legal, investment or other professional advice.
The full issue is attached.
I hope you find it interesting.
Bell Howley Perrotton LLP is a limited liability partnership registered in England and Wales under number OC353525. Registered office: 20-22 Wenlock Road, London, N1 7GU. VAT number: GB 991703492.
BHP Advisory Ltd is a company registered in England and Wales under number 15240401. Registered office: 53 Davies Street, Mayfair, London, W1K 5JH. VAT number: GB 484722859.
