September 18, 2026
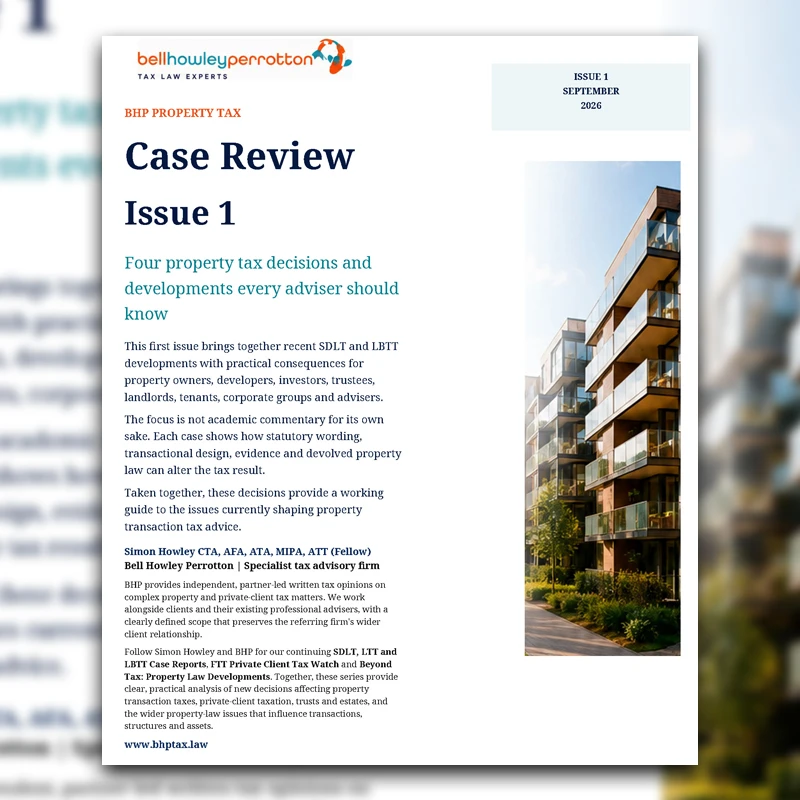
I’m pleased to share the first issue of our new BHP Property Tax Case Review which you can download here.
Property transaction taxes continue to generate some of the most technically interesting — and practically important — decisions affecting property owners, investors, developers and their professional advisers.
In this new series, we will bring together significant developments across SDLT, LTT and LBTT, looking beyond the headline result to examine the reasoning, the legislation involved and, importantly, what each decision means in practice.
Issue 1 brings together several recent cases covering some very different areas of property taxation, including:
- the meaning of “suitable for use as a dwelling” and the developing position following Mudan;
- section 75A and SDLT group relief;
- the treatment of transitional leases under LBTT;
- DOTAS and property incorporation arrangements; and
the wider practical lessons emerging for taxpayers and advisers.
As with our Beyond Tax: Property Law Developments series, we do not simply intend to report what the courts and tribunals have decided.
We want to explain why the decision matters, where its limits lie, and what advisers should consider when encountering the same issues in real transactions.
That distinction is particularly important with property taxes. An FTT decision may be highly instructive without creating binding precedent; an apparently favourable judgment may turn on unusually specific facts; and an appeal can materially change the position.
We will therefore continue to follow these cases as they develop and update future issues where there is an important appeal, judgment or change in HMRC, WRA or Revenue Scotland practice.
I hope you find it useful!
Bell Howley Perrotton LLP is a limited liability partnership registered in England and Wales under number OC353525. Registered office: 20-22 Wenlock Road, London, N1 7GU. VAT number: GB 991703492.
BHP Advisory Ltd is a company registered in England and Wales under number 15240401. Registered office: 53 Davies Street, Mayfair, London, W1K 5JH. VAT number: GB 484722859.
