October 8, 2026
Before June 2024, purchasers often argued that an annexe was a separate dwelling to obtain Multiple Dwellings Relief. Following MDR’s abolition, the same conclusion can now produce the opposite result: a sufficiently valuable second dwelling may bring the whole acquisition within the higher rates for additional dwellings.
Case at a glance
Decision: John Smith v HMRC [2026] UKFTT 1351 (TC), released 18 September 2026.
Issue: Whether a detached pool house was suitable for use as a single dwelling for Multiple Dwellings Relief.
Outcome: The taxpayer’s appeal was dismissed; £80,750 of SDLT remained payable.
Reason: The annexe met basic domestic needs, but its relationship with the shared pool prevented objectively realistic occupation with sufficient privacy and security.
Status: First-tier Tribunal; persuasive, not binding. No appeal has been publicly confirmed as at 8 October 2026.
Key point: Dwelling status is no longer automatically beneficial. After MDR, a valuable non-subsidiary annexe may trigger HRAD on the whole acquisition.
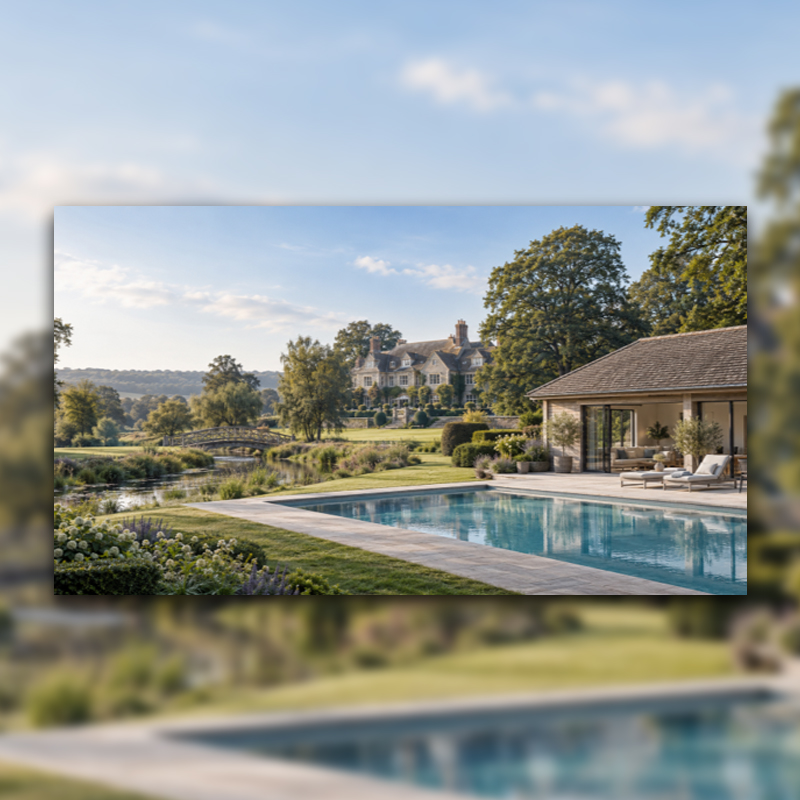
John Smith bought Huntbourne, an eight-bedroom house in approximately three acres near Tenterden, for £2.6 million on 14 December 2023. The grounds also contained a detached, single-storey building described in the sales brochure as a pool house. The taxpayer later claimed Multiple Dwellings Relief on the basis that the main house and pool house were two dwellings. The difference between the competing calculations was £80,750.
MDR was abolished for transactions completing on or after 1 June 2024, subject to limited transitional protection for contracts exchanged on or before 6 March 2024. Smith therefore concerns a historic relief claim. Its present importance lies elsewhere: the same dwelling analysis is relevant when deciding whether an acquisition containing a main house and annexe is itself a higher-rates transaction under Schedule 4ZA Finance Act 2003.
The annexe was more than 200 feet from the main house, separated by a stream and accessed by its own driveway. It had lockable entrances, parking, underfloor heating, its own oil tank and boiler, a water stop-tap and a fuse board. Inside were a main room, plant room, sauna room, shower room and a separate lavatory and basin.
The Tribunal found that the main room could accommodate a single bed and modest seating area as well as the kitchen facilities. The sauna room could provide storage. There were facilities to prepare, consume and clear away food, and private washing and toilet facilities. These findings materially supported the taxpayer: the annexe could meet the occupant’s basic domestic living needs.
Several familiar administrative indicators pointed the other way. The two buildings shared a council-tax assessment, postal address, electricity meter, water meter and Land Registry title. The Tribunal gave those matters only limited weight. Practical arrangements could allocate utility costs and deal with post, while a single title is not conclusive. Equally, the annexe’s separate heating controls, stop-tap and fuse board supported independence but were not determinative.
The physical and practical relationship between the annexe and the swimming pool proved decisive. Its French doors opened directly onto the pool terrace. The pool was an important amenity of the main house, yet the annexe contained the shower, changing and toilet facilities most likely to be used by anyone swimming.
The taxpayer proposed two possible occupation arrangements. Under the first, occupiers of the main house would surrender access to the pool. Under the second, both households would share it. The Tribunal accepted that the first arrangement could resolve the privacy issue, but considered it objectively unrealistic that occupiers of an impressive main house would relinquish a significant amenity. Shared use was also unrealistic as a basis for independent occupation: in practice, the main-house occupants would be likely to use the annexe’s facilities, materially intruding upon the annexe occupier’s privacy and security.
This is the most important part of the judgment. A theoretically possible licence or house rule is not enough. Any proposed occupation terms must be objectively realistic for occupiers generally, not merely workable for relatives, friends or unusually accommodating occupants.
The Tribunal applied the Upper Tribunal’s binding approach in Fiander and Brower v HMRC [2021] UKUT 156 (TCC). Suitability is assessed objectively at completion. The building must be fit for use as a separate, self-contained living unit, meeting basic living needs with a degree of privacy, self-sufficiency and security consistent with a single dwelling. The exercise is multi-factorial and does not turn on any one checklist item.
Smith does not create a new test and, as a First-tier Tribunal decision, it is not binding. Its value lies in the disciplined application of Fiander. The judgment also warns against constructing a case by selecting favourable findings from unrelated First-tier Tribunal decisions. Different properties produce different factual balances.
Before MDR was abolished, establishing that an annexe was a separate dwelling could reduce the SDLT liability. The position is now potentially reversed. For an individual purchasing two or more dwellings, paragraph 5 Schedule 4ZA can make the whole transaction subject to HRAD where at least two purchased dwellings satisfy the statutory conditions, including that neither is subsidiary to the other.
This matters most where the purchaser would otherwise avoid HRAD—for example, because this is the purchaser’s first property or a qualifying replacement of an only or main residence. If the annexe is a separate, non-subsidiary dwelling, the acquisition of two dwellings can itself trigger the higher rates. If the annexe is not a separate dwelling, the transaction is analysed as the acquisition of one dwelling. If it is separate but subsidiary, the Schedule 4ZA tests are also applied as though only one dwelling had been purchased.
A purchased dwelling is subsidiary where it is within the same building as, or within the grounds of, another purchased dwelling and the consideration attributable to that principal dwelling, on a just and reasonable basis, is at least two-thirds of the total consideration attributable to all the purchased dwellings.
Accordingly, an annexe representing no more than one-third of the combined value can be a separate dwelling but still be disregarded as subsidiary when determining whether the acquisition itself triggers HRAD. If it exceeds one-third of the combined value, the principal dwelling represents less than two-thirds and the protection is lost. With only two dwellings, an annexe exceeding one-third of their combined value is equivalent to it exceeding half the value of the principal dwelling.
The valuation is therefore capable of deciding the tax treatment. It should be supported by a reasoned, just-and-reasonable apportionment rather than a convenient figure adopted solely for the SDLT return.
The correct analysis is sequential. First, decide whether the annexe is objectively suitable for use as a separate dwelling at completion, applying Fiander and the fact-sensitive reasoning illustrated by Smith. Secondly, if it is a dwelling, determine whether it is subsidiary by examining its location and the just-and-reasonable allocation of consideration. Thirdly, if it is not subsidiary, apply the remaining paragraph 5 conditions to the purchased dwellings and establish whether the whole transaction is a higher-rates transaction.
The purchaser’s wider property ownership must still be reviewed. Where only one dwelling is treated as purchased, HRAD may apply under the ordinary single-dwelling rules if the purchaser already owns another dwelling and is not replacing an only or main residence. For companies and certain other non-individual purchasers, separate Schedule 4ZA rules apply and the subsidiary-dwelling analysis should not be assumed to produce the same outcome.
A room-by-room facilities schedule remains useful, but it must be accompanied by an occupation analysis covering shared gardens, pools, driveways, entrances, plant rooms, meters and access to essential facilities. Smith shows why a kitchen and bathroom are not a complete answer: the building must work as genuinely independent accommodation for occupiers generally.
The evidence should be contemporaneous with completion. Plans and photographs should show sightlines, access routes, locks, boundaries and the precise relationship between the secondary building and shared amenities. If independence depends upon contractual restrictions, the terms should be settled before completion and tested for practical and commercial realism.
Where the subsidiary threshold may be material, obtain valuation evidence that separately identifies the principal dwelling, its attributable garden and grounds, the annexe and any grounds attributable to it. The advice should record both the dwelling analysis and the basis of the apportionment.
· Reframe annexe training: separate-dwelling status may now increase rather than reduce SDLT following the abolition of MDR.
· Add Smith beneath Fiander, expressly identifying it as persuasive first-instance authority on privacy, security and realistic occupation.
· Use a three-stage checklist covering dwelling status, subsidiary status and the remaining purchaser and transaction conditions under Schedule 4ZA.
· State the statutory threshold accurately: the principal dwelling must represent at least two-thirds of the combined value.
· Require dated plans and photographs showing the secondary building’s access, glazing, sightlines and relationship to shared facilities.
· Obtain and retain a just-and-reasonable valuation apportionment where the one-third combined-value boundary may be material.
· Record why any proposed restrictions on use by the main house are realistic for occupiers generally, rather than merely possible on paper.
Smith is not merely a footnote to an abolished relief. It provides a current warning that domestic facilities do not automatically create a separate dwelling and that dwelling status is no longer necessarily tax-favourable. The pool house could support sleeping, washing, cooking and storage, but the practical use of the pool made genuinely independent occupation unrealistic.
For present transactions, advisers should not stop after answering whether there is a second dwelling. They must then test whether it is subsidiary and whether the acquisition satisfies the remaining HRAD conditions. A conclusion that once supported MDR may now expose the whole consideration to the 5% higher-rates surcharge.
Primary authority: John Smith v HMRC [2026] UKFTT 1351 (TC)
Binding authority: Fiander and Brower v HMRC [2021] UKUT 156 (TCC)
HMRC guidance: SDLTM09766 — purchases of two or more dwellings
Bell Howley Perrotton LLP is a limited liability partnership registered in England and Wales under number OC353525. Registered office: 20-22 Wenlock Road, London, N1 7GU. VAT number: GB 991703492.
BHP Advisory Ltd is a company registered in England and Wales under number 15240401. Registered office: 53 Davies Street, Mayfair, London, W1K 5JH. VAT number: GB 484722859.
