March 16, 2026
Solicitors
Over the past few weeks I have had the pleasure of visiting a number of firms, including Thomas Legal, HM3 Legal, Herrington Carmichael, Bowling Law and VAS Solicitors, speaking with teams about areas where SDLT risk can arise in conveyancing transactions. It has been great to continue these conversations in person and share some practical guidance on how firms can help de-risk matters where tax issues arise.
Following some of those discussions, I would like to highlight two recent tribunal decisions relevant to mixed-use claims.
Two recent First-tier Tribunal decisions demonstrate how fact-specific the “garden and grounds” analysis can be.
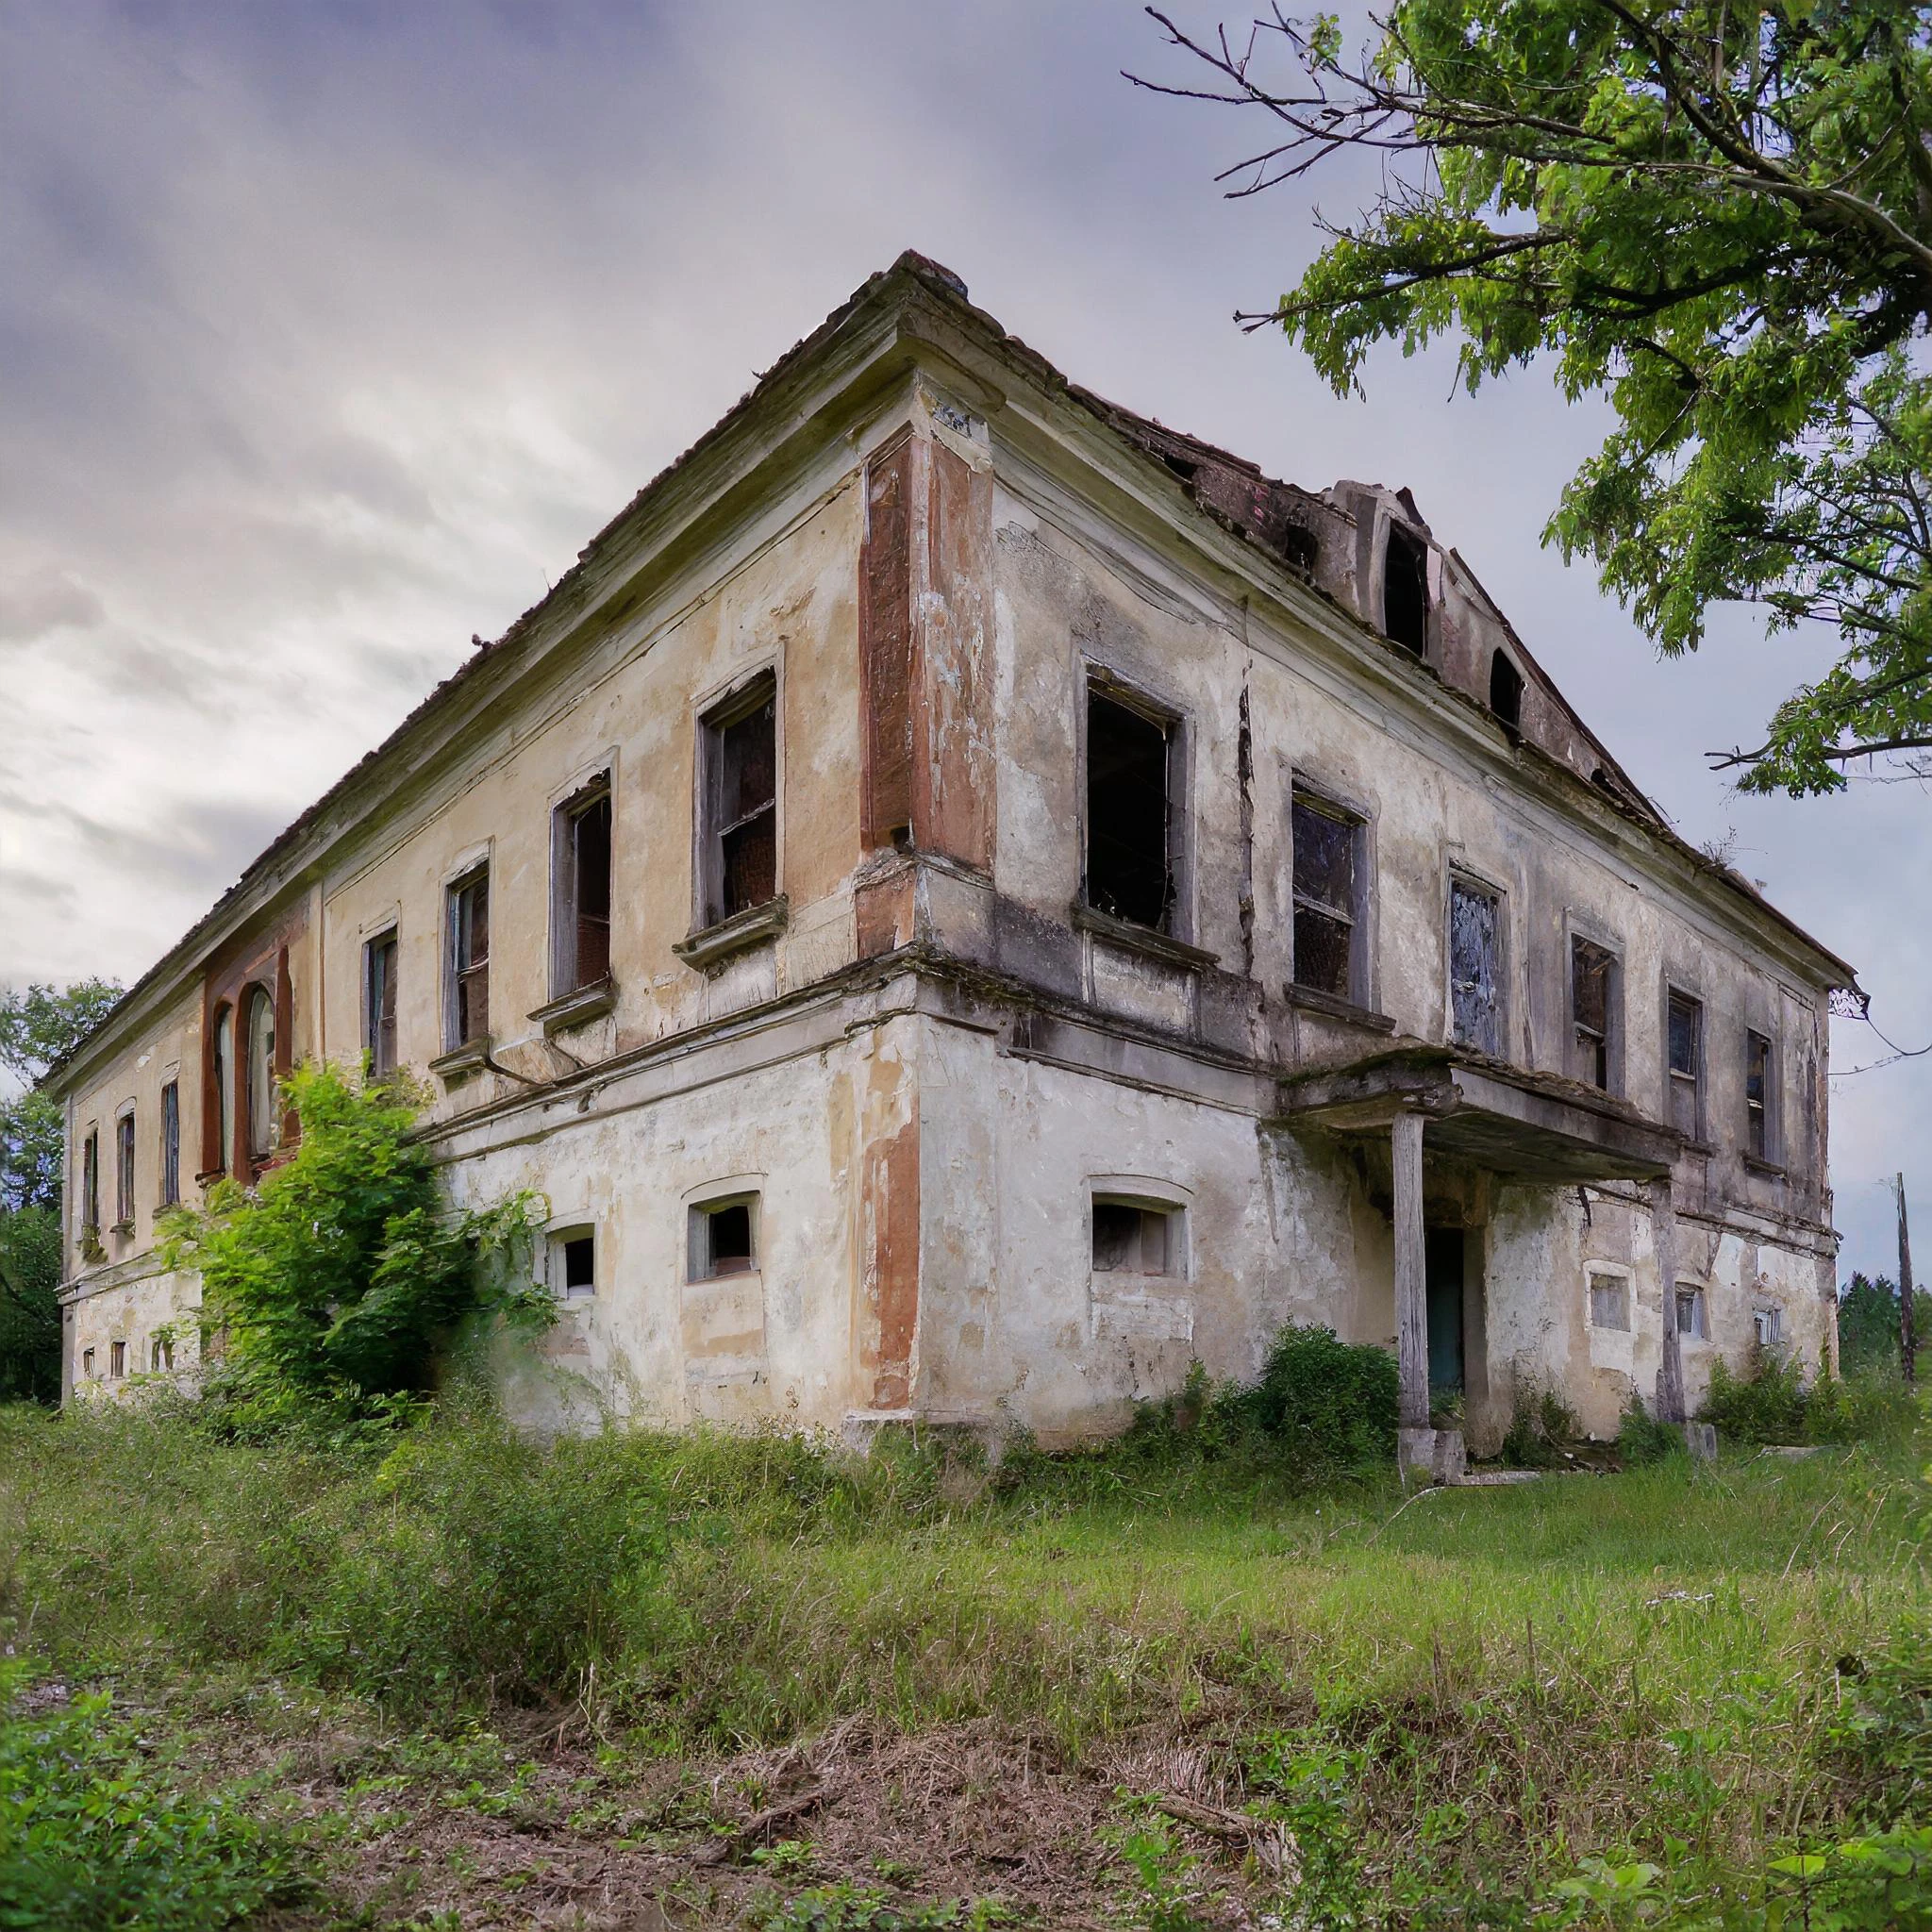
In Ferguson v HMRC, a substantial residential property included a small paddock which had been used for many years by a neighbouring livery business under a grazing licence. The paddock was not visible from the house and had not been used by the owners themselves. Despite this long-standing commercial use, the Tribunal concluded that the paddock still formed part of the grounds of the dwelling. A key factor was that the paddock did not have independent access and could only be reached via the main property.
In contrast, the Tribunal reached the opposite conclusion in Wood and Veitch v HMRC. The property included a section of busy Thames towpath and an area of riverside land beyond the garden wall. The judge accepted that the towpath was heavily used by the public and that the owners could not realistically use or control it as part of their garden. As a result, it did not form part of the residential grounds and the transaction qualified as mixed-use, resulting in a substantial SDLT refund.
Together these decisions are a helpful reminder that each transaction turns on its own facts. Factors such as access, separation from the dwelling, privacy and the practical use of the land can all be critical when assessing whether land forms part of the “grounds” of a property.
We are also continuing to receive queries about HMRC’s tax adviser registration requirements. The legislation is coming in from the 1st of April 2026, but registration with HMRC will commence on the 18th May 2026.
Some commentary in the market has suggested that firms must outsource tax advice in order to comply with the new rules. This is not the case. Firms do not need to panic or assume SDLT advice must be outsourced — the requirements are primarily aimed at ensuring advisers are appropriately registered and operating transparently.
Many firms are comfortable dealing with straightforward points themselves, but where more complex issues arise, particularly around SDLT, CGT or IHT implications within property transactions, we are always happy to support solicitors by providing specialist tax advice and helping to de-risk transactions.
If you would like to discuss a particular matter, please feel free to contact me at amanda@bhptax.law in the first instance. Our SDLT team can also be reached at freya@bhptax.law.
If you would like to arrange a training session for your team on SDLT or property tax risk areas, Olivia would be very happy to assist and can be contacted at olivia@bhptax.law.
Bell Howley Perrotton LLP is a limited liability partnership registered in England and Wales under number OC353525. Registered office: 20-22 Wenlock Road, London, N1 7GU. VAT number: GB 991703492.
BHP Advisory Ltd is a company registered in England and Wales under number 15240401. Registered office: 53 Davies Street, Mayfair, London, W1K 5JH. VAT number: GB 484722859.
